What Google's Q3 results mean for your SEM budget
The honest answer to that question has two halves. The first is to keep the budget where the intent is and change what you can prove about it, before the next campaign review. The second, and the one many advertisers will take, is to wait — to leave the account as it is until the auction, AI Mode monetisation and the new budget controls settle into something you can read again. Two Digiday briefings and a WARC analysis describe more queries arriving while the revenue per query gets harder to read, which is why the choice is worth making deliberately rather than by default.
A sem agency that reports only what Google's back office shows leaves that problem unsolved, and so does one that reports impressions instead of signed deals. The rest of this article sorts out which platform changes should change your brief to your agency, and which can wait.
Key takeaways
- Alphabet reported total Q3 revenues nearing $127.6 billion, up 25% year-on-year, yet its shares fell approximately 12.6% the following day.
- Search & other revenue grew 12% to $63.35 billion, while advertising fell to approximately 64% of Alphabet's revenue from 72%.
- WARC found the largest brands' combined ad-to-sales ratio at 5.5% in 2025, down from 6.1% in 2019, while their ad spend rose 56%.
- Google added optional channel prioritisation and budget allocation controls across its ad channels.
Table of contents
- Why a bigger Google does not mean an easier search account
- What the numbers say about revenue per query
- How AI Mode changes the query a buyer types
- What Prebid's auction proposal would change
- What WARC's ad-to-sales data says about budgets
- SEO and SEM: what is the difference?
- What Topkee's closed loop would change
- What to ask your agency to prove instead
- Reading a quarterly report as a buyer
- What waits, and what does not
- Topkee's view: where the data loop should close
- FAQ
Why a bigger Google does not mean an easier search account
The Q3 report contained both facts at once. Alphabet said its search queries were growing at the fastest annual rate in five years and reported total revenues nearing $127.6 billion, up 25% year-on-year. Digiday's readers saw the other half in the share price: Alphabet shares fell approximately 12.6% the next day, shedding close to half a trillion dollars of value.
For an advertiser, the useful question is not whether Google is growing. It is whether the part of Google your budget runs through is growing in the way your last campaign review assumed. Search & other revenue increased 12% to $63.35 billion. That is healthy for Google and tells you nothing about whether the clicks bought by your Singapore account turned into enquiries.
What the numbers say about revenue per query
The briefing filed that week described the quarter as a curveball for the usual story about AI eating Google's business. Philipp Schindler, Alphabet's chief business officer, attributed the slower growth to AI Mode's relatively limited monetisation at that stage.
Advertising as a whole made up approximately 64% of Alphabet's revenue, down from 72% a year earlier, with YouTube at $11.2 billion and Google Network at $7.45 billion for the quarter. Google Network grew just 1.4% in the period, and traffic acquisition costs rose about 10% to $16.4 billion overall.
Why TAC matters to a buyer
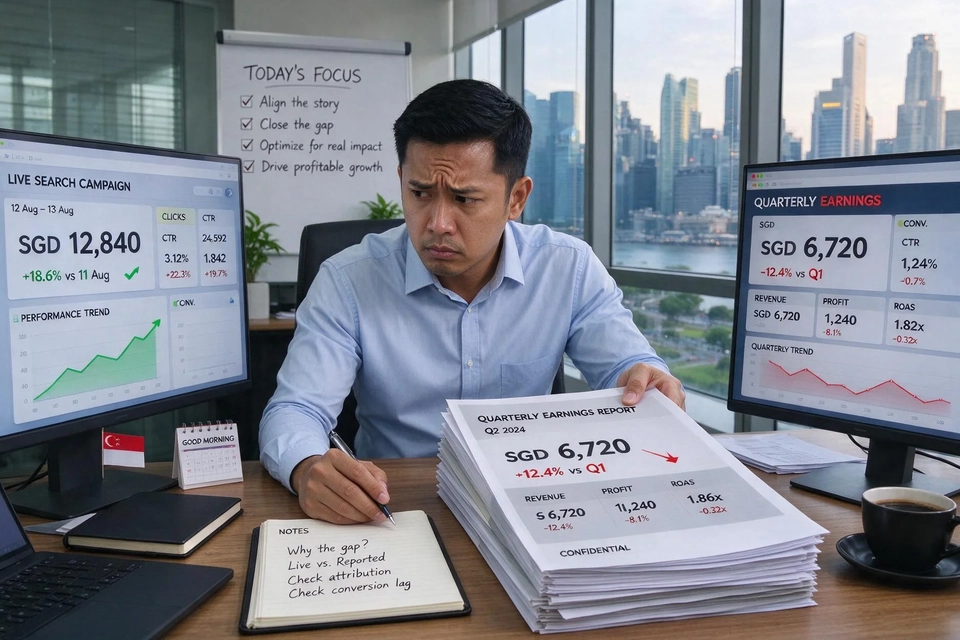
Digiday made the point that higher impression prices can hide shrinking volumes. The same mechanism runs through search: a rising cost per click can mask a stable cost per conversion, or the reverse, depending on what you count as the conversion. That is a reason to stop treating click-through rate as a health metric.
If your last few Search reports show a flat cost per lead and a rising cost per click, the conversion definition is the place to look first.
How AI Mode changes the query a buyer types
Sundar Pichai, Alphabet's CEO, told analysts that AI Mode queries are on average three times longer than traditional searches and that roughly one in five involves voice, images or documents. Philipp Schindler, Alphabet's chief business officer, told the earnings call that AI Mode's comparatively limited monetisation had contributed to the slowdown in growth.
Longer queries with mixed inputs change what a search account does. A buyer who types a full sentence about a service in their own words is further along than someone typing two words, and further from any exact-match keyword you can bid on. Google Search Ads' account structure was built around keywords, so on an AI Mode surface the landing page and the copy carry more of the qualifying work.
What you cannot yet see in the platform
Google's own AI reporting covers AI Overviews and AI Mode impressions. It does not show the prompts, the follow-up questions or which of those visits converted, so any decision to put budget into conversational surfaces needs your own analytics to back it.
What Prebid's auction proposal would change
An earlier briefing in the same series covered a Prebid proposal previewed at a New York event. Under the current arrangement, Prebid runs its auction and passes the winning bid to an ad server, usually Google's Ad Manager, where it competes with AdX demand. The proposal reverses the flow: ad servers would bid into Prebid.
Digiday noted that the proposals await final sign-off after a public consultation, that Prebid targets early 2027 for formalisation and that Google has not committed. The briefing's own view is that the proposal goes after one control point while the real levers stay put.
Why this barely touches your search budget
Prebid's debate is about the sell side of programmatic display: which exchange runs the final auction. Your Google Search Ads budget does not clear through that auction. If a display or retargeting partner says the proposal will change your results this year, ask which auction their inventory goes through; the answer, or its absence, shows how much of your budget that partner controls.
What it does show is where the power in ad tech sits. Whichever party controls the point where the decision is made controls the economics, and the firms around Google are trying to move that point. The same question applies to your account: who decides which channel gets the budget?
The control Google did hand over
In mid-October, Google rolled out optional channel prioritisation and budget allocation controls across Search, Shopping, Performance Max and Demand Gen. Advertisers can mark higher-priority channels to receive budget first and cap the share that goes to secondary ones, rather than leaving the split to automation.
This is the change most likely to alter a Singapore SME's account before the end of the year. If you cap Performance Max's share, something has to decide what the secondary channel spends on. An sem agency singapore that never separated branded search from non-branded can set those caps, but cannot tell you what to expect from them.
What WARC's ad-to-sales data says about budgets
The earlier briefing also carried WARC figures. Among 25 of the world's largest brands, the combined advertising-to-sales ratio fell to 5.5% in 2025 from 6.1% in 2019, even though their combined advertising expenditure rose 56% over the same period. Had Alphabet, Netflix, Meta and Microsoft held their combined 2019 ratio, WARC estimates they would have generated $52 billion more in advertising expenditure. Among consumer goods companies, collective ad spend grew 36% between 2019 and 2025.
From an SME's desk, that is a story about large budgets growing slower than the revenue behind them. The pressure is the one your finance director applies: marketing spend as a share of sales, with the agency retainer inside it.
Why the ratio is not the whole answer
A ratio says nothing about what the spend bought. WARC's comparison is a good frame for the conversation with finance and a poor target on its own; the number beside it is the cost of a signed deal, measured the same way in each period.
SEO and SEM: what is the difference?
Readers ask what separates the two often enough that it belongs here early. SEM is paid search: you bid in an auction for a place above or beside the results, and you pay for each click. SEO is organic visibility: you earn the position through content, structure and links, and you pay for it in time and work rather than per click.
The platform changes above act on the paid side. Channel budget allocation moves Google Search Ads' media spend, while an AI Mode answer citing a page affects organic visibility, and the paid auction around that answer may not exist yet.
| SEM (paid search) | SEO (organic search) | |
|---|---|---|
| Who decides placement | The auction and your bid | The ranking system and your content |
| What you pay for | Each click | The work, not the click |
| How fast it moves | Within a day of a budget change | Over weeks and months |
| What changes it most this quarter | Budget controls, AI Mode surfaces | AI answers citing pages |
| Where the proof of return should sit | Your signed-deal data | Your signed-deal data |
The last row is the one this year's numbers argue for. Both channels are usually judged on a platform's report, and both deserve a better yardstick.
What to ask your agency to prove instead
The buyer's decision in front of you is narrow. Do you renegotiate what your SEM agency measures and controls, or wait until the auction, AI Mode monetisation and the new budget controls settle?
Waiting is defensible only if your reports already say what a signed deal costs. Most do not. Ask a sem agency singapore for these four items in writing before the next review:
- A cost per signed deal for the last complete quarter, calculated as signed-deal value divided by ad spend, with the data source named.
- The channel split of that spend, and who decided it, before and after the mid-October budget controls.
- The share of conversions that fell inside the platform's attribution window, and how many real deals fell outside it.
- The list of actions taken after the last audit, with a status for each.
An agency that cannot produce the first item is reporting on the platform's behalf. A sem agency that separates branded from non-branded search and shows the landing-page drop-off is in a different category.
Who this advice does not suit
If your average deal closes within a week and your CRM already writes conversions back to Google, the gap is smaller. Spend the effort on audience expansion or creative testing instead. The advice fits B2B services, training providers and any business with a quote or a site visit between the click and the payment.
Reading a quarterly report as a buyer
A sem agency should be able to show the same ledger across the budget controls, the AI Mode shift and the auction debate. That is the practical test of whether the renegotiation is worth the meeting. The habit a buyer takes from Digiday's briefing is to separate the platform's growth from the share of it that reaches the advertiser's account. Alphabet's revenue and your cost per signed deal can move in opposite directions, and only the second one appears in your ledger.
What waits, and what does not
The channel controls went live in mid-October and need a decision this quarter: review the default split, decide whether Search is prioritised over Performance Max and Demand Gen, and cap the secondary channels with a review date. AI Mode monetisation is not settled, and a Singapore account likely has limited exposure for now; keep the landing page and copy strong enough to do the qualifying work a keyword match once did. Prebid's proposal can wait until its early 2027 formalisation target, since the auction it changes is not the one your search budget enters.
Topkee's view: where the data loop should close
Topkee's own reporting argues that the gap these briefings describe is usually a plumbing problem. In a closed-loop marketing architecture, the ad platform, CRM, website and e-commerce data are connected so the click, the enquiry, the quote and the signed deal sit in one place. Topkee Cloud and the TTO data platform hold that data in the client's own tenant, and qualified conversions go back to Google and Meta so bidding learns from deals rather than form fills.
The Campaign Intelligence Report puts four data sources on one ruler: Google Ads, Yahoo Ads, Facebook Ads and GA4, with GA4 as the row where organic traffic enters. Its ROAS denominator is signed-deal value divided by ad spend, which is also the first item on the list above. The report can show how much of a click's spend survives each step to a deal, rather than stopping at the platform's last click.
Two limits in Google's own system are worth naming here. Smart Bidding allocates traffic only inside Google's system, so the budget split between Google and another platform has to be managed outside it. Google's attribution window for modelled conversions is fixed at a set length, so B2B orders that close later never enter the model. Both are reasons to keep the channel weighting and the attribution in a system you control.
Data ownership is the other half of it. Accounts, data and optimisation history stay with the client rather than in a dashboard that ends when a retainer does. The renegotiation above only works when those numbers belong to you and stay with you.
For a starting point, revenue tracking and lead conversion tracking sets how a lead becomes a deal in the ledger, and selecting the right SEM agency covers the questions that separate a reporting shop from one that runs the loop.
FAQ
Is SEM still worth it while Google's AI search monetises at a lower rate?
Search & other revenue grew 12% to $63.35 billion, so the auction is still working for advertisers who measure deals rather than clicks. The rate at which AI Mode monetises affects Google's revenue mix and the mix of placements you may see. It does not change whether a buyer typing a service query can become a customer.
What is the difference between SEO and SEM?
SEM is paid placement in a search auction, billed per click. SEO is earning an organic position through content and site structure, billed in work rather than per visit. Both are judged on the same question in this article: what a signed deal costs once the visit is traced to revenue.
Does Prebid's auction proposal affect my Google Ads spend?
Not directly. The proposal changes how ad servers bid into Prebid's programmatic auction, which is sell-side inventory rather than the search auction. Its formalisation target is early 2027 and Google has not committed. Watch it at a quarterly interval.
Should I cap Performance Max's share of my budget?
Those channel controls let you, but the cap only helps if you know what each channel returns. Set a cap after you can report cost per signed deal by channel. Before that, capping shifts spend without telling you whether the shift helped.
How many days does Google count a conversion for?
Google's attribution window for modelled conversions is fixed at a set length, so orders that close outside it do not enter the bidding model. A B2B advertiser should reconcile platform conversions against its own CRM before trusting the cost per acquisition, and ask a sem agency singapore which system holds that reconciliation.
Sources
- Ad Tech Briefing (series page), Digiday, 3 November 2026. https://digiday.com/series/digiday-ad-tech-briefing/
- Ronan Shields, "Ad Tech Briefing: Google's AI-reckoning", Digiday, 3 November 2026. https://digiday.com/marketing/ad-tech-briefing-googles-ai-reckoning/
- Ronan Shields, "Ad Tech Briefing: Can flipping the ad auction wrest control of ad tech from Google?", Digiday, 20 October 2026. https://digiday.com/marketing/ad-tech-briefing-can-flipping-the-ad-auction-wrest-control-of-ad-tech-from-google/
- "Reach Customers Across YouTube & Search - Google Ads", Google, undated. https://www.google.com/ads/